
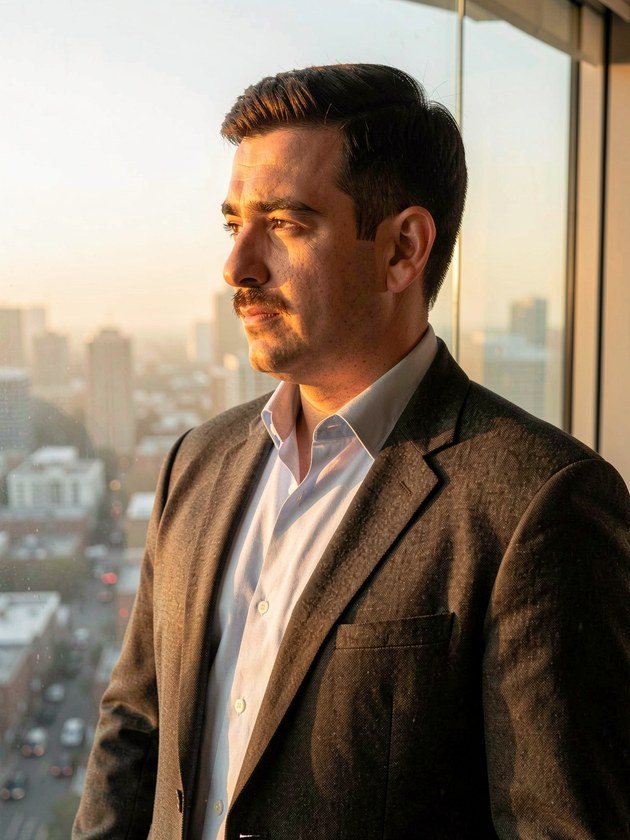
PhD, Imperial College London, 2011
Zamrik Quant Lab
Dr. T. Zamrik heads Zamrik Quant Research, whose work is the mathematics of deciding under uncertainty: when to act, how hard, and what a crowd of such decisions does to a market. The tools are stochastic analysis, optimal control and stopping, and mean field games. The papers here are working papers and technical notes; the essays turn the same mathematics into stories, a wildfire season, a flock of starlings, a price racing to a barrier, with models you can run in the browser.
Research
52 working papers and technical notes, each with its own page, abstract and PDF.
Notebooks
13 Jupyter notebooks: every figure made by its own code, to download or to run on Kaggle.
Tools
3 tools: live boards that each answer one practical question, with your settings saved in the link.
Essays
80 essays: a story first, then the mathematics, with data, code and live models.
Selected papers
The papers with a DOI, archived on Zenodo:
- What Does a Nonlinear Fokker–Planck Equation Buy a Mean Field Game?: Frontiers, Tails, Capacity, Congestion and Herding in Crowds Whose Agents Touch. Discussion Paper, 2026. DOI 10.5281/zenodo.23249488 · code on GitHub
- Littlewood's Rule for a Home Battery: Optimal Storage on Ontario's Ultra-Low Overnight Plan, When to Install One, and Why It Does Not Pay Without Solar. Working Paper, 2026. DOI 10.5281/zenodo.23128038
- A Leverage Cap on an Inconsistent Investor: Equilibrium Mean-Variance Control under a Stochastic Opportunity Set. Preprint, 2026. DOI 10.5281/zenodo.22929860
- Diffusions with Stochastic Resetting: Nonequilibrium Steady States and the Optimal Restart Rate. Working Paper, 2026. DOI 10.5281/zenodo.22852567
- The Derived Time Stop: Exiting a Swing Trade under Drift Uncertainty and a Deadline. Working Paper, 2026. DOI 10.5281/zenodo.22972015 · code on GitHub
- The Square-Root Wall: When a Brownian Path Reaches c Standard Deviations of Its Own Age. Technical Note, 2025. DOI 10.5281/zenodo.23306052 · code on GitHub
Latest
- Paper: A Continuum Theory of Channeling in Espresso and the Grind Paradox (16 October 2026)
- Notebook: How Often Should You Look at Your Portfolio? (18 October 2026)
- Tool: Will You Pass the Prop-Firm Challenge? (12 October 2026)
- Blog: The Earthquake That Changes the Clock (19 October 2026)
Areas
Market Microstructure & Trading · Derivatives & Volatility · Optimal Control & Decision · Stochastic Analysis · Applied MathematicsHow to cite
The form, with the paper’s own details:
T. Zamrik ({year}). {title}. {document type}, {serial}. {DOI where the paper has one, otherwise its address on this site}.
For example:
T. Zamrik (2026). A Leverage Cap on an Inconsistent Investor. Preprint, PR-2026-51037481. https://doi.org/10.5281/zenodo.22929860
The same, as BibTeX:
@misc{zamrik2026leverage,
  author = {Zamrik, T.},
  title  = {A Leverage Cap on an Inconsistent Investor},
  year   = {2026},
  note   = {Preprint, PR-2026-51037481},
  doi    = {10.5281/zenodo.22929860},
  url    = {https://zamrik.com/research-items/pr-2026-51037481/}
}
Elsewhere
- Code: github.com/Zamrik-Quant-Research
- Notebooks: kaggle.com/tzamrik
- Papers with a DOI: Zenodo
- ORCID: orcid.org/0009-0009-2792-1647
- Google Scholar: scholar.google.com · T. Zamrik
- Telegram: t.me/zamrik_research (new posts, with a short film)
- YouTube: youtube.com/@zamrikquantresearch (short films of the posts and notebooks)
- Facebook: facebook.com · Zamrik Quant Research (every new post, notebook and tool)
Contact: info@zamrik.com